


Customer Checkout

Your customer enters their payment details, and Fluid Pay turns the card data into a secure token.

A secure, cloud-based payment gateway that helps businesses accept credit cards, ACH, and digital wallets online, in store, and on the go.
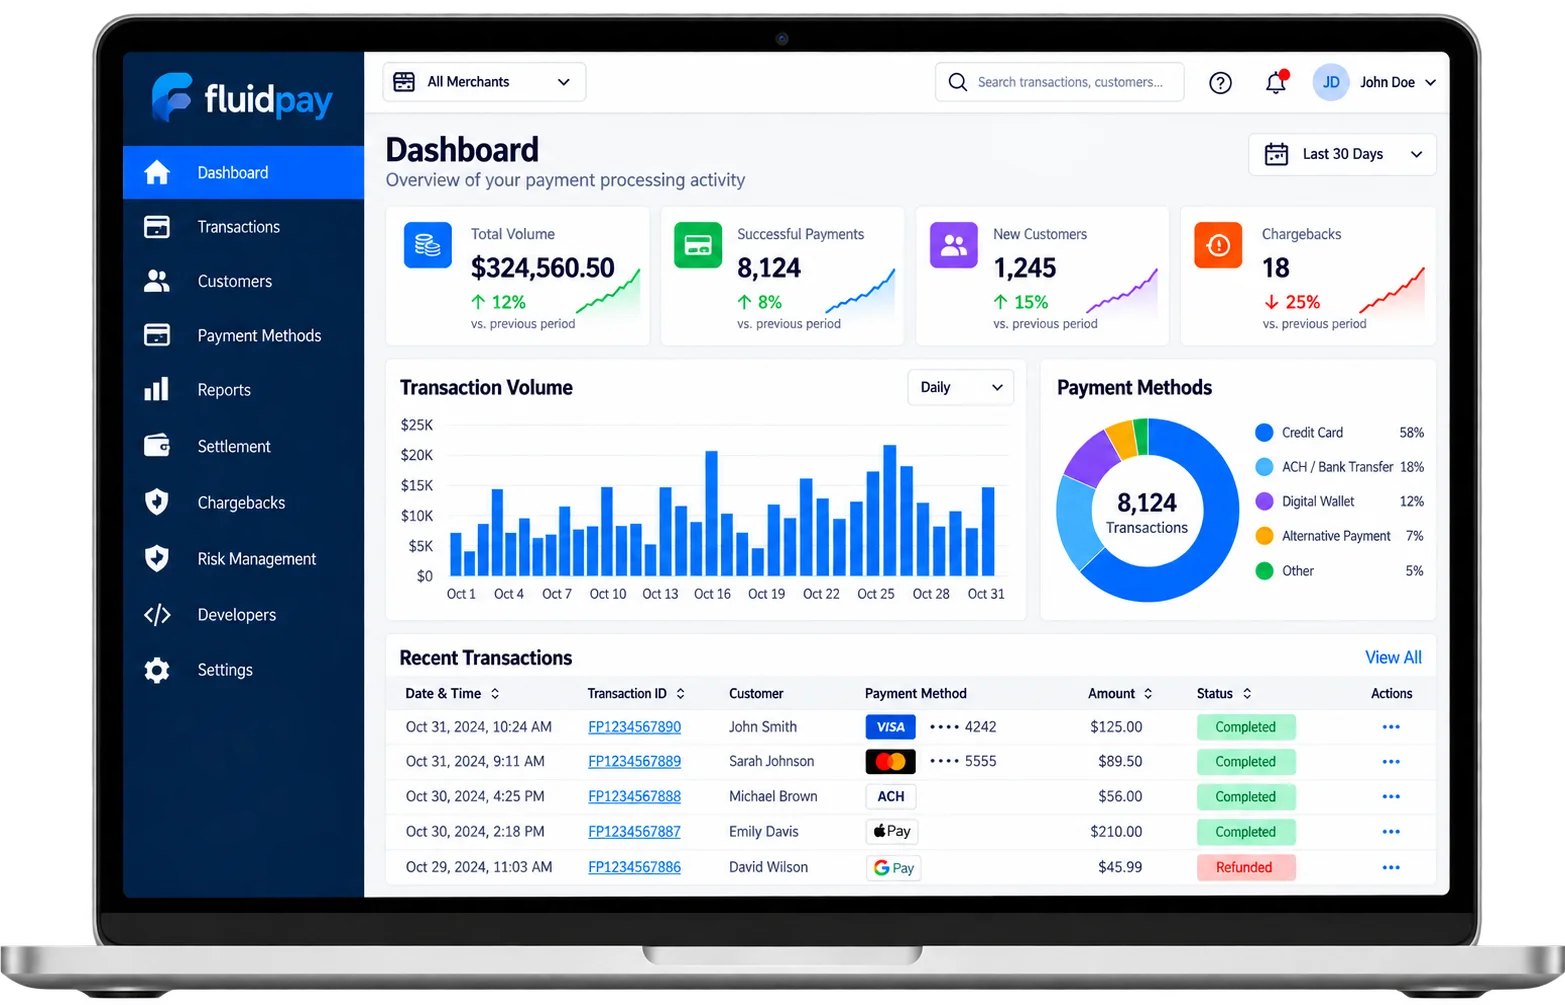
Support all major credit cards, ACH and eCheck, and popular digital wallets.



Everything you need to run your business and get paid.

Run subscriptions with plans, retries, and dunning for card and ACH payments on one engine.

Take card and ACH payments from any browser on one simple form.

Flag risky transactions with custom rules, velocity filters, and machine learning scoring.

Save card and ACH details as secure tokens for faster checkout and repeat sales.

Accept chip, tap, and mobile payments in store or on the go with Processa POS.

Track decline codes, fraud attempts, and settlement timing, then filter and export your data.
Fluid Pay connects with popular ecommerce platforms and offers a developer-friendly REST API.
Your customer enters their payment details, and Fluid Pay turns the card data into a secure token.
Fluid Pay screens the transaction for fraud and sends it to your processor and the issuing bank.
The bank approves the transaction and funds are authorized.
Funds are settled to your merchant account as scheduled.

Fluid Pay gives you the flexibility to connect your merchant account to your website, shopping cart, or custom checkout while you accept payments online securely.

From small shops to multi-location brands, Fluid Pay grows with you.

Online checkout through WooCommerce, Magento, or a hosted Fluid Cart™ page.

Accept chip and tap payments in store and on the go with Processa POS.

Manage recurring billing and memberships with automatic card updates.

Take phone, mail, and invoice payments with the Virtual Terminal and E-Invoicing.


The Fluid Pay payment gateway is a cloud-based gateway that connects a business’s website, software, virtual terminal, or payment device to its merchant account and payment processor. Fluid Pay® LLC, a Franklin, Tennessee company operating since 2017, runs card-present, eCommerce, recurring, and batch payments through one API and one dashboard on Google Cloud with multi-region failover.
Fluid Pay is a payment gateway, not a merchant account. It does not board or underwrite merchants directly, so every merchant needs an approved merchant account and a compatible processor to receive funds. AllayPay sets up your merchant account, so you hold your own MID, and connects it to Fluid Pay.
Fluid Pay supports major credit and debit cards, ACH and eCheck payments, Apple Pay, and Google Pay. Through its Bead integration, announced July 14, 2026, Fluid Pay merchants can also accept PayPal, Venmo, Klarna, and cryptocurrency, with transactions settling in U.S. dollars. Availability depends on the merchant account, processor, and integration setup.
Yes. Fluid Pay offers hosted payment fields, a hosted “Pay Now” checkout page, a hosted shopping cart called Fluid Cart™, pre-built cart integrations, and a REST API. Merchants can choose a simple hosted option or build a custom checkout.
Yes. Fluid Pay lists ready-made integrations for WooCommerce and Magento, a Gravity Forms integration for WordPress, and QuickBooks™ PaySync for accounting. Its REST API can also connect payments to custom websites, apps, and billing systems. Setup guides for the WooCommerce, Magento, and Gravity Forms plugins are published in the Fluid Pay developer documentation.
Yes. The Fluid Pay Virtual Terminal lets authorized users take card and ACH payments from any internet browser, with both payment types on the same form. It works well for payments that do not go through an online checkout.
Yes. Fluid Pay Recurring Billing runs plans, retries, and dunning for card and ACH payments on one engine. Merchants can also add discounts and add-ons to adjust a subscription amount by a set dollar amount or a percentage.
Yes. The Fluid Pay Customer Vault uses tokenization to store card and ACH details on the gateway. Merchants can charge saved customers for repeat purchases and recurring payments without keeping full card numbers in their own software.
Fluid Pay Simple Payments is a hosted “Pay Now” checkout page that merchants can set up from the gateway without writing code. It runs on a custom URL and carries the merchant’s branding.
The Fluid Pay Tokenizer is a set of pre-built, hosted payment fields that merchants add to their checkout. Card data travels from the customer’s browser straight to the gateway through a secure frame, and the merchant’s server receives a token instead of the card data. Fluid Pay states that this setup keeps merchants at the SAQ A level of PCI assessment.
Yes. Fluid Pay E-Invoicing lets merchants send invoices by email and SMS. Each invoice includes a payment link, and the merchant can track completed payments in the gateway.
Yes. Merchants can share payment links through E-Invoicing, Simple Payments, and Fluid Cart™ “Buy Now” links. These options help merchants collect payments without building a full shopping cart.
Yes. Fluid Pay supports ACH and eCheck payments across its Virtual Terminal, Customer Vault, Recurring Billing, Batch Processing, and cart integrations. ACH access depends on underwriting approval and account setup.
Fluid Pay includes WatchDog, a fraud engine that uses rules, velocity filters, and machine learning scoring to approve or decline transactions before or after authorization. Fluid Pay also offers WatchDog Community Rules, crowd-sourced filters for BIN-attack and card-spinning patterns, and AttackDog, a machine learning tool for fraud detection. AllayPay pairs these gateway tools with its own chargeback monitoring services.
Yes. Fluid Pay states that it is a PCI DSS Level 1 Service Provider, a certification it dates to 2019. Hosted fields, tokenization, and the Customer Vault can reduce the amount of card data a business handles. Merchants must still complete the PCI requirements that apply to their own payment setup.
Yes. Fluid Pay offers an Automatic Account Updater that works with the Customer Vault and Recurring Billing. One enrollment covers Visa Account Updater, Mastercard Automatic Billing Updater, Discover, and American Express, and updated cards are applied before the next scheduled charge. Accounts closed without a replacement card are not updated and go to dunning instead.
Yes. Authorized users can void transactions that are still pending settlement, and Fluid Pay processes these as auth reversals where applicable. Users can also refund settled transactions, including multiple partial refunds up to the original settled amount.
Yes. Fluid Pay offers a REST API that uses JSON, public developer documentation, and a sandbox environment for testing. Sandbox transactions return simulated responses and do not go out for processing.
In many cases, yes. The Fluid Pay Gateway Emulator accepts requests in legacy gateway formats, runs them through Fluid Pay, and returns responses in the format the existing application expects. Fluid Pay says most merchants migrate by changing endpoints, not codebases. Fluid Pay maintains the list of supported legacy formats separately, so confirm your current gateway is on it before planning a cutover.
Yes. Fluid Pay supports larger operations with batch processing by CSV upload, Level 3 processing for B2B and government sales, dashboard analytics, and a cloud setup on Google Cloud with multi-region failover. Fluid Pay reports 99.99% gateway uptime on a rolling 12-month basis, and its processor-agnostic design lets a business switch acquirers without replacing the gateway.
Yes. High-risk merchants can use the Fluid Pay payment gateway once an acquiring bank approves their merchant account. Fluid Pay does not underwrite merchants, and its processor-agnostic gateway connects to multiple acquirers, so the acquirer sets eligibility, not the gateway. AllayPay works with high-risk merchants in industries such as CBD and Delta 8, nutraceuticals, travel, and firearms, and pairs approved accounts with Fluid Pay, NMI, or Authorize.net.
Fluid Pay does not list gateway prices on its website because it sells only through partners, so the cost is set by the provider that sets up your account. Request a free quote from AllayPay to see the cost for your business. Fluid Pay also supports cash discount, dual pricing, and surcharging programs that can offset card processing costs.
Fluid Pay surcharging applies to credit cards only and caps the surcharge at 3.00%. The gateway checks the card BIN as the number is entered and removes the surcharge for debit and prepaid cards and in states that prohibit surcharging. The fee must be itemized on every checkout page and receipt, and Fluid Pay notes that card brands require registration at least 30 days in advance through the acquirer.
AllayPay offers Fluid Pay alongside Authorize.net and NMI, so merchants can compare three gateways through one provider. Fluid Pay works only through partners and does not sell to merchants directly. AllayPay, Inc., based in Plantation, Florida and operating since 2016, serves more than 1,000 active merchants, is a registered ISO/MSP of Fifth Third Bank, N.A., and coordinates underwriting, gateway setup, fraud settings, and integration support through a dedicated U.S.-based account manager.
Fluid Pay, Authorize.net, and NMI are all payment gateways that AllayPay offers. Fluid Pay is partner-only, states it has never boarded a merchant directly, and adds Bead acceptance for PayPal, Venmo, and Klarna. Authorize.net sells directly to merchants. NMI serves ISOs, software companies, banks, and payment facilitators and lists 150+ processor connections.
To get started with Fluid Pay through AllayPay, request a free quote and share your business type, website, expected monthly volume, and payment channels. AllayPay offers same-day approvals for many businesses and boards U.S. merchants only. Once the merchant account is approved, AllayPay sets up Fluid Pay for online checkout, virtual terminal, ACH, invoicing, recurring billing, or in-person payments.
Get Started
Tell us about your business and we’ll match you with the right banking partner and the right pricing, usually within one business day.
 No long-term contracts. Cancel anytime.
Service and support at a fraction of the cost.
Dedicated U.S.-based account manager included.


